You didn’t go to law school to become a bookkeeper. Nobody did.
And yet here you are, a managing partner or solo practitioner, occasionally lying awake wondering if your trust account is actually right. Not “probably fine.” Right. Because in this one specific corner of running a law firm, “probably fine” isn’t a status you’re allowed to have.
If you’ve ever typed some version of “is trust accounting really that big a deal” into Google at 11pm, welcome. Let’s talk about it honestly.
At Luma Accounting, headquartered in Portland, Oregon, we handle bookkeeping and accounting for small law firms dealing with exactly this kind of thing.
What trust accounting actually is, in plain English
Every dollar a client hands you before you’ve earned it, a retainer, a settlement that’s about to be disbursed, a filing fee they advanced, doesn’t belong to your firm yet. It belongs to them. Your job is to hold it, track it, and move it correctly until it’s actually yours or theirs to use.
That money lives in a trust account (often called an IOLTA account) that is legally, completely separate from your firm’s operating account. Not “separate in spirit.” Separate in the eyes of your state bar.
Simple in concept. Genuinely easy to get quietly wrong in practice, especially when the person tracking it is also the person invoicing clients, managing the calendar, and running the front desk.
The part nobody explains well: three-way reconciliation
Here’s the basic idea, stripped of jargon.
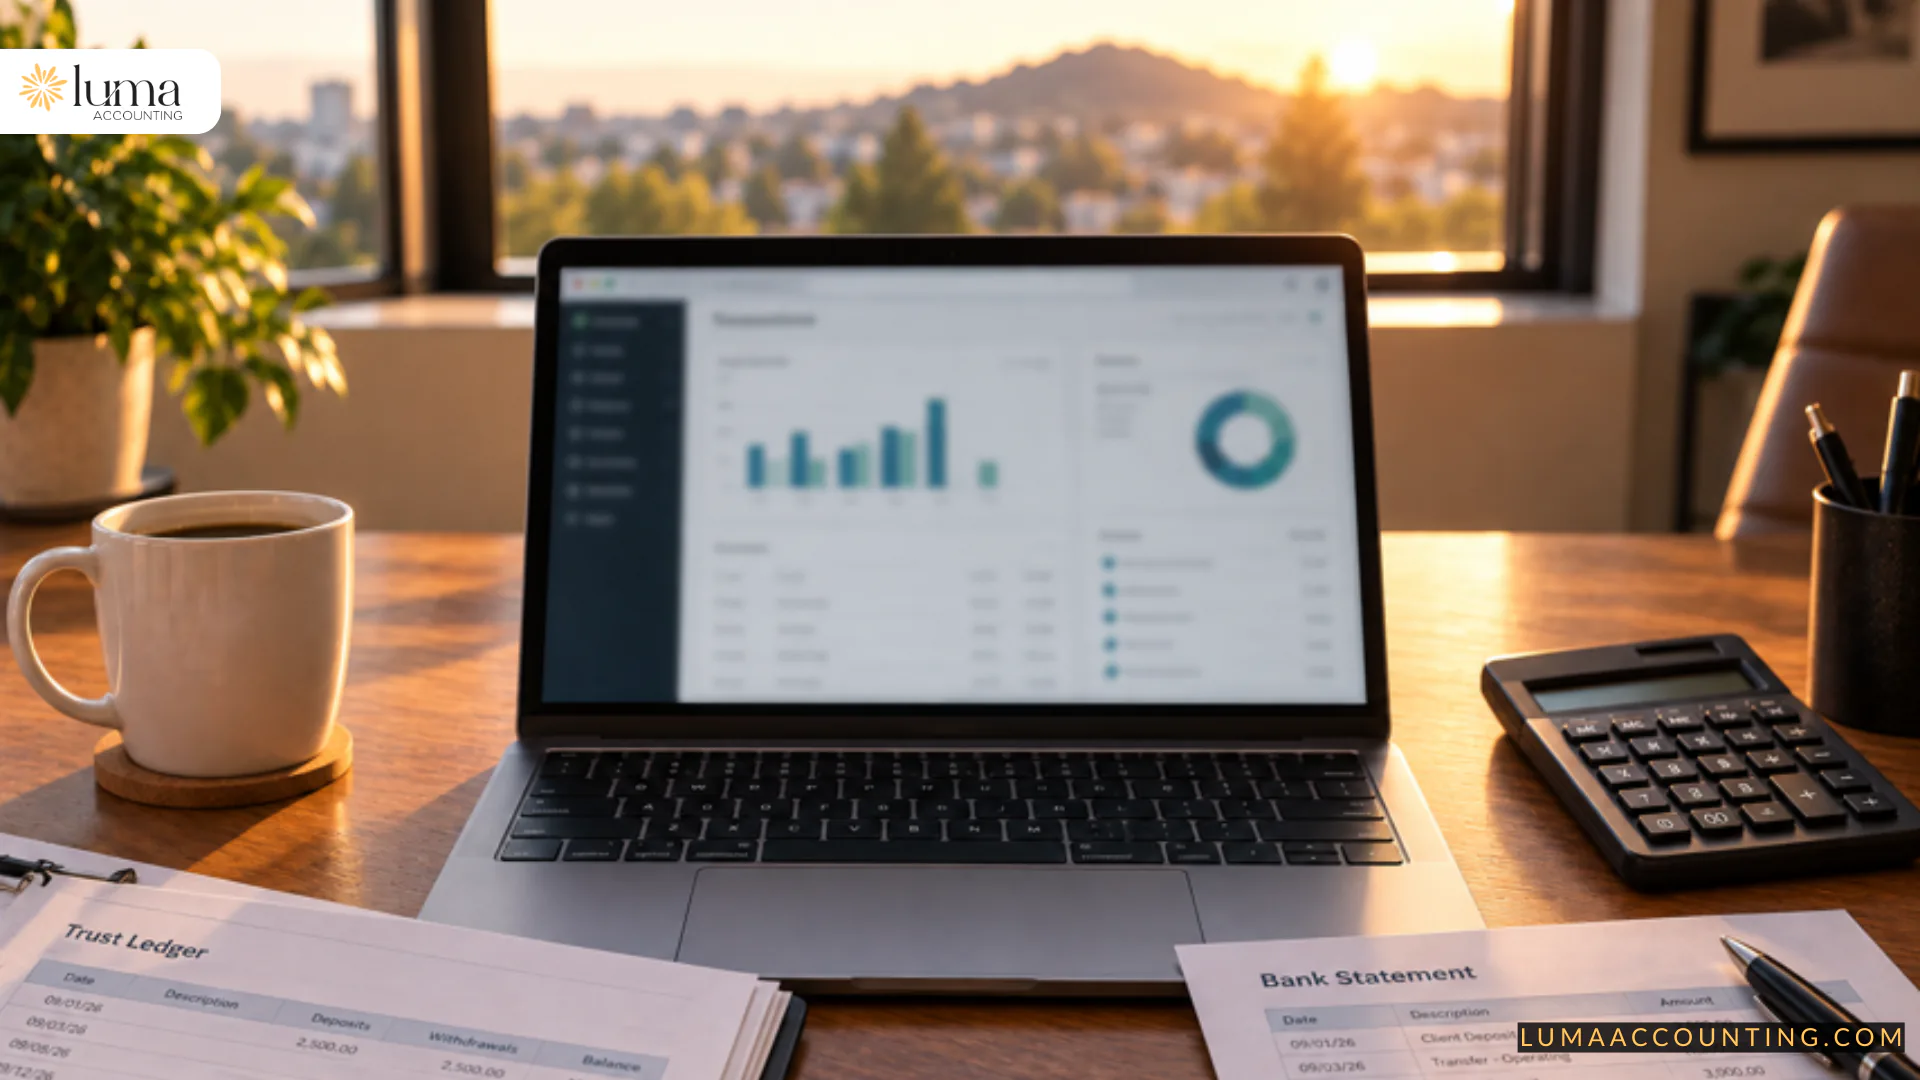
Every month, three numbers need to match, exactly:
- Your trust bank statement. What the bank says is actually sitting in the account.
- Your trust ledger. What your books say should be in the account, in total.
- Your client subsidiary ledgers. What each individual client’s slice of that total should be, added up client by client.
If all three agree, your trust account is in balance and you can prove it. If any one of them is off, even by a few dollars, you don’t technically know whose money is short. That’s the part that should get your attention. A trust account discrepancy isn’t really a math problem. It’s a “which client’s funds are we not able to account for” problem.
This isn’t a once-a-year, tax-season kind of task. It has to happen every single month, on every trust account you hold, whether you have three clients in trust or thirty.
A note on QuickBooks Online specifically, because we live here
QuickBooks Online is our home base, and we’ll be honest with you. Straight out of the box, QBO is a little humble about trust accounting. It’ll happily give you a trust bank account and a trust liability account, both of which absolutely need to exist and stay separate from your operating funds, no exceptions. What it won’t do on its own is tell you which slice of that trust account belongs to which client. That third leg of the stool, the client-by-client detail, has to come from somewhere.
This is exactly why we don’t blink when a firm shows up running Clio, Smokeball, or ZenCase. We’ve gotten to know all three, because most small firms already have one of them handling billing and case management long before they ever meet us, and honestly, we think that’s a good thing.
A little Glow Session on how each one actually talks to QBO:
Clio plays nice and syncs trust transactions straight into your QBO ledger, so activity flows through without you or your admin typing it twice. One thing worth knowing, and it’s the kind of detail we live for. Clio syncs at the account level, not down into QBO sub-accounts, so how your chart of accounts is built still matters quite a bit.
Smokeball does its own thing, and does it well. It keeps the entire trust ledger, including every client’s individual balance, right there inside Smokeball, and only sends the summary journal entries over to QBO. Translation. QBO becomes your general ledger, while Smokeball stays the true system of record for who owns what in trust.
ZenCase (recently rebranded SurePoint Practice Pro, in case that name crosses your desk) integrates its billing and trust activity with QBO too, with its own dedicated path for bringing trust history over cleanly.
Here’s the part we want every managing partner to actually hear. Different plumbing, same non-negotiable requirement underneath. Not one of these platforms runs your three-way reconciliation for you. They make it possible to do quickly and correctly, sure, but somebody still has to sit down every single month, pull the numbers from both systems, and confirm they agree down to the penny. That’s the step that quietly stops happening at busy firms, fancy integration or not. And that’s the step we exist to own.
The liability side, said plainly
We’ll say the quiet part out loud, because pretending it isn’t there doesn’t serve you.
Mishandling client trust funds, even unintentionally, even because your well-meaning office admin fell behind during a busy season, is not treated like a normal bookkeeping error. It’s treated as a professional responsibility issue. Trust account problems are consistently one of the most common sources of state bar disciplinary complaints, and the consequences run the full range: fines, mandatory audits, suspension, and in serious or repeated cases, disbarment.
The part that catches good attorneys off guard is that intent rarely matters much here. “We didn’t mean to commingle funds” and “nobody was reconciling it consistently” tend to land you in the same conversation with your bar’s ethics counsel. Bar rules generally hold the attorney personally responsible for trust account accuracy, even when someone else on the team is doing the day-to-day entries.
That’s not meant to scare you. It’s meant to explain why so many managing partners describe this specific worry as the thing that follows them home.
Why this keeps slipping through the cracks at small firms
You’re not disorganized. You’re just doing five jobs.
At most small and solo firms, there’s no in-house accountant. Someone smart and capable, often an office manager or paralegal, is handling billing and invoicing beautifully, while trust reconciliation either happens inconsistently, gets done incorrectly, or quietly doesn’t happen at all. Not from negligence. From bandwidth.
QBO gets set up once, by someone who’s since moved on, and nobody’s fully sure it’s configured the way trust accounting actually requires. Sound familiar?
What actually fixes this
Real financial clarity, not a scramble every time your bar association mentions an audit.
At Luma, this is exactly the gap we sit in for small law firms. Accounting + Technology + Process means your three-way trust reconciliation gets done correctly, every month, by someone who already understands legal accounting rather than someone learning it on your dime. We work alongside your existing admin instead of replacing them, so the person who’s great at billing keeps doing that, and the compliance-critical piece finally has an owner.
The Glow Session where a managing partner tells us “I finally feel like the accounting is in good hands” is one of our favorite moments. It happens more often than you’d think, because the relief is almost always bigger than the client expected.
If you’re not sure where you stand right now
You don’t need a dramatic mess to start. You just need a next step.
If you’ve been quietly wondering whether your trust account would hold up under a bar audit today, that’s worth a conversation, not a spiral. We’re always happy to talk through what a clean trust accounting process actually looks like for a firm your size.
You became an attorney to practice law. Let us handle the numbers, including the part that keeps you compliant, so you can get back to building the firm you actually set out to build.
Luma Accounting serves small law firms across the U.S. from our home base in Portland, Oregon, with bookkeeping, accounting, and trust accounting support built around the systems you already use. If you’re ready to put a real owner on this process, get started with Team Luma.
A quick note: this post is general information to help you understand the basics, not legal advice specific to your firm or state bar rules. Your bar association’s trust accounting guidelines are always the final word.